Holiday Hours

In observance of Veterans Day, SouthState locations will be closed on Wednesday, November 11. SouthState Customer Care will be open 8 a.m. - 5 p.m. ET. Transactions initiated or scheduled on a holiday are processed the next business day.

Learn More
South State Bank Logo
  • About Us
  • Help
  • Locations
Login
South State Bank Logo
Login
Login
About Us
  • Careers
  • News
  • Investor Relations
  • Corporate Stewardship
  • NMLS #403455
Help
  • Lost/Stolen Card
  • FAQs
  • Self-Service Forms
  • Fraud and Security
  • Routing Number: 063114030
Bank on the Go
  • Download our Mobile App
  • Download on the App StoreDownload on theApp Store
  • Get it on Google PlayGET IT ONGoogle Play
Connect with Us
  • (800) 277-2175
  • Contact Us
  • ATM/Branch Locations
  • facebook
  • twitter
  • linkedin
SouthState Bank
  • FDIC Coverage
  • Consumer Privacy Notice
  • Online Privacy Policy
  • Terms of Use
  • CRA
  • Accessibility
  • My Money Matters
  • Member FDIC

©2026 SouthState Bank, N.A.

South State Bank Logo - Mobile
instagram
  • youtube
  • The Cost of Waiting to Adopt Instant Payments

    6/16/2026 - by Judson McAdams - Commercial Banking

    Working together on instant payments

    Instant Payments Are Valuable When:

    • Timing is critical
    • Immediate confirmation is required
    • Payments fall outside of traditional banking hours*
    • Cash flow optimization is a priority
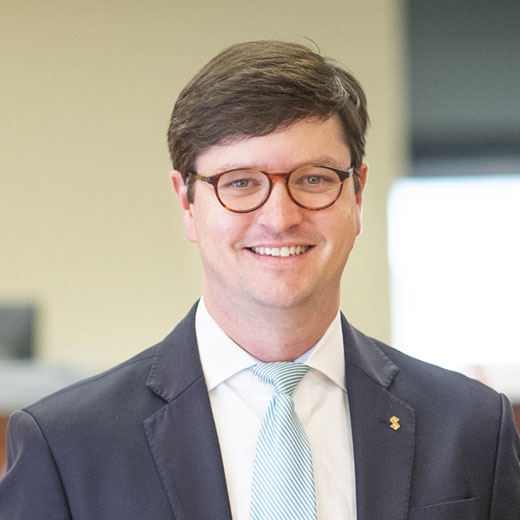
    A man in a navy blazer and striped tie smiles in a professional headshot with a blurred office background.

    Judson McAdams is currently EVP, Director of Treasury Management and Payment Solutions for SouthState Bank. He is spearheading the effort to make Instant Payments fully available to SouthState’s commercial banking customers later this year. With 20 years of commercial banking experience, he has held many different roles, including Head of Business Banking at Park Sterling Bank and Portfolio Manager for SunTrust Robinson- Humphrey.

    Read more articles from Judson McAdams

    Shareshare with facebookshare with x, formerly known as twittershare with linkedinshare with email
    Print

    Related Articles


    • 5/9/2025Faster Payments, Better Business: The Benefits of Instant Payments
    • 6/10/2026Best Payment Method: ACH, Wires, or Instant Payments?
    • 6/27/2024Introducing Instant Payments Receive
    • 11/13/2025Payroll Meets Progress: Instant Payments are Here
    • 9/17/2025SouthState Expands Instant Payment Capabilities

    The Competitive Advantage of Acting Now

    Instant Payments are not a future concept. They are already here, already in use, and already shaping expectations. Businesses that take a proactive approach today position themselves to improve cash flow, reduce operational risks and strengthen relationships with vendors, employees and customers. Those that wait may not feel the impact immediately. But over time, the cost of delayed adoption can add up in missed efficiencies, lost opportunities, and reduced agility.

    The question is no longer whether Instant Payments will become part of everyday business operations. The infrastructure is in place at many banks, adoption is growing, and use cases are expanding. The real question is how and when your business will take advantage of it. In a world where money can move in seconds, waiting days is no longer just a delay – it’s a disadvantage.

    *For more information about Instant Payment availability as well as operational and timing specifications, contact your banker
    For decades, businesses have relied on the same core payment methods to move money: ACH, wire transfers, and checks. While those systems have evolved incrementally, such as the introduction of same-day ACH, the fundamental structure of how payments move in the United States has remained largely unchanged. That is, until now.

    Instant Payments represent the first true modernization of payment rails in nearly 50 years. They introduce something businesses have never had before at scale: the ability to send and receive money in real time, with immediate confirmation and finality. Yet despite the innovation, adoption has been gradual. Many businesses continue to rely on familiar methods, taking a ”wait and see” approach rather than actively exploring how Instant Payments could fit into their operations. The question is no longer whether Instant Payments will become part of the financial ecosystem, but what it’s costing your business to wait.

    What Are Instant Payments and Why Do They Matter?

    At their core, Instant Payments designed to be exactly what they sound like: payments that settle in seconds, rather than hours or days. Powered by two primary networks, the RTP (Real-Time Payments) network and the Federal Reserve’s FedNow service, Instant Payments operate continuously, 24 hours a day, 7 days a week, 365 days a year. *At many banks, there are no cutoff times, no overnight delays, and no waiting for the next business day; however, speed is only part of the story. Instant Payments also introduce several important structural differences that reshape how money moves.
    1. Funds are available to the recipient immediately.*
    2. Once a payment is sent, it cannot be reversed.
    3. Payments can only be initiated by the sender.
    These enhanced features do more than accelerate payments – they fundamentally improve certainty, visibility, and control.

     

    If Instant Payments Are So Powerful, Why Isn’t Everyone Using Them?

    Despite the clear advantages, adoption has not happened overnight. Businesses are deeply accustomed to their existing payment processes. ACH, wires, and checks, while slower, are still widely accepted. For many organizations, there’s little perceived urgency to change something that appears to be functioning adequately. Instant Payments are not meant to replace all payment types. Instead, they introduce a new option, one that is particularly valuable in situations where timing, certainty, and precision matter most.


    The Real Cost of Waiting

    Cash Flow: When a business issues a payment by check, even under normal circumstances, it may take several days for that check to arrive, be deposited, and clear. During that time, the recipient has no access to those funds. Now, multiply that delay across dozens or hundreds of transactions. The result is a consistent lag in cash availability that can ripple through the entire organization. Money that is ”in transit” is money that isn’t working for your business. Instant Payment networks operate continuously.  Depending on the financial institution, eligible customers may be able to send and receive payments in real-time with confirmation.

    Efficiency: Traditional payment methods often require additional oversight and manual effort. Teams may spend time tracking payments, reconciling transactions with incomplete data and following up on delayed or missing payments. Instant Payments simplify this process. With immediate confirmation and standardized data, businesses can streamline reconciliation and reduce administrative burden.

    Timeliness: One of the most overlooked constraints of traditional payment systems is their reliance on banking hours. ACH and wire transfers are bound by daily cutoff times, weekday processing schedules and limited weekend availability. This creates friction in situations where business continues outside those windows. Instant Payment networks operate continuously.  Depending on the financial institution, eligible customers may be able to send and receive payments in real-time with confirmation.
     

    Addressing the Risk Misconception

    One of the most common concerns about Instant Payments is the perception that faster payments increase fraud risk. In practice, the opposite may be true. Instant Payments are designed with several built-in features that support risk management. They utilize the credit push structure where only the account holder can initiate a payment. Instant Payments also use pre-transaction validation where fraud checks occur before the payment is released. While no payment method is entirely risk-free, early industry data suggests that Instant Payments can offer a strong security profile when implemented and used appropriately.


    A Smarter Way to Think About Payments

    The rise of Instant Payments doesn’t mean businesses should abandon ACH, checks or wires. Each payment method still has a role to play. Instead of adopting a single payment method strategy, organizations should adopt a multi-rail approach, selecting the most appropriate payment method for each specific situation. Instant Payments are particularly valuable when timing is critical, immediate confirmation is required, payments fall outside of traditional banking hours*, or cash flow optimization is a priority. By incorporating Instant Payments into their toolkit, businesses gain greater flexibility and control over how and when money moves.