Protecting Your Home: Hurricanes and Insurance Coverage
8/9/2024 (Updated: 7/6/2026) - by Maddi Shuler - Personal Banking
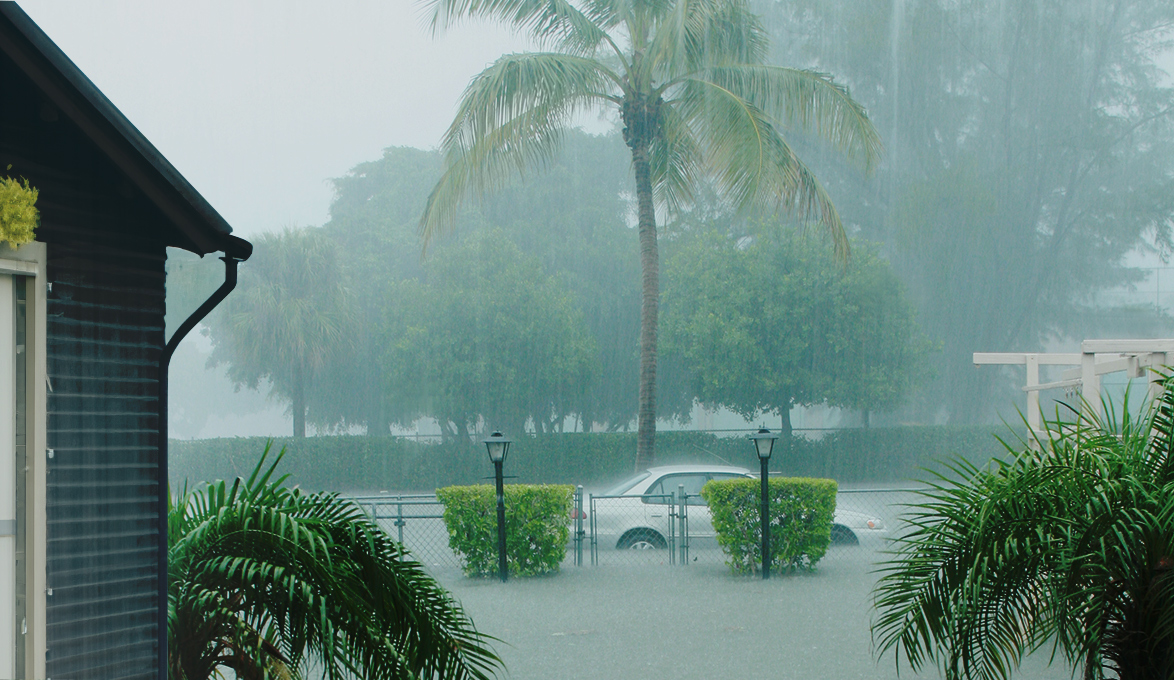

If you’re unsure about your home’s coverage, the best course of action is to verify your protection.
Share


Print
8/9/2024 (Updated: 7/6/2026) - by Maddi Shuler - Personal Banking
Fall décor is arriving on shelves in stores across the Southeast. Before we can celebrate cooler temperatures and the first day of school, we must pay attention to the ongoing hurricane season.
A survey from the Insurance Information Institute shows the South is the most prepared when it comes to having an evacuation plan for severe weather, with 58% of homeowners knowing where they’ll relocate. After gathering batteries and potable water, have you checked on your homeowner’s insurance to prepare for damage from a hurricane?
Hurricane season, which runs from June 1 – November 30, comes with torrential rain, flooding, high winds and much more. It can be stressful to try and predict the severity or path of the latest hurricane, but you can prepare your home and finances with adequate coverage.
Take the following steps before a storm heads your way.
The aftermath of a weather event is not the time to be questioning your property’s coverage. Review your policy online today, perhaps on your lunch break or while waiting for your grocery pickup order.
Have more in-depth concerns about your policy? Talk to your insurance agent in person or on the phone so you can ask questions in real time.
We all have busy schedules, especially this time of year. Setting aside time to verify your coverage, however, can alleviate future problems.
”If you’re unsure about your home’s coverage, the best course of action is to verify your protection. This can be an annual practice, but it’s especially important to take care of before hurricane season,” says, SouthState Director of Mortgage Operations Michael Owens.
Most coverage plans do protect your home in the event of a natural disaster, though it’s likely not spelled out as ”hurricane insurance.” Depending on whether you live on the coast in Wilmington or more inland in Raleigh, your policy stipulates what type of damage is covered, and you’ll want to verify hurricane scenarios are included. Certain policy sections need a closer look when it comes to windstorm damage and flooding.
Verify that your policy includes enough coverage to rebuild your home in the event of a total loss. This amount will differ from the current real estate value.
Look closely at your deductibles as your policy likely lists separate deductibles for hurricanes and/or windstorms. In this case, there is a threshold that moves the deductible amount from wind to hurricane.
You will also want to verify your possessions are covered in the event of damage to your home. Do you have antique heirlooms or expensive entertainment equipment? Talk to your provider about extending your coverage to replace these items.
No one wants to think about dealing with a sewer backup. Heavy stormwaters can cause this issue, even if you’re maintaining your plumbing. Explore coverage options with your insurance provider to include initial cleanup, mold mitigation and flooring replacement.
Did you know that just 5 inches of flood water can cost upwards of $45,000 to repair?1 Whether you live in a low-lying area or near a body of water, flood waters bring significant damage.
Flooding is a common problem during hurricane season, but flood insurance isn’t automatically included in most homeowners’ policies. Check your policy today and consider buying an additional policy if you’re not sufficiently covered.
You may live away from the coast in Charlotte or Richmond, for example, but don’t underestimate your risk of flood damage. The National Flood Insurance Program2 says 40% of claims from 2014 to 2018 came from people outside of high-risk flood areas.
In addition to heavy rainfall from a hurricane or tropical storm, flooding can result from summer thunderstorms, broken water mains or poor drainage systems. It’s a good investment year-round.
According to the NFIP, several of your home’s factors affect how much you will pay for flood insurance.
Ready to purchase flood insurance? The NFIP offers a guide to determining eligibility and local providers.
According to the III survey, only 47% of homeowners have made an inventory of their assets in case of damage. Having a documented list of valuables and property is key if you need to make an insurance claim after a weather event.
Both renters and homeowners should create an inventory and keep a digital copy in their financial records. It’s also a good idea to purchase a watertight document case for original copies of vital paperwork.
Need to know more about preparing for a storm? Use our guide.
Renters should prepare for severe weather, too. Ask your landlord or management company if they have sufficient coverage.
Personally, consider a renters policy to protect your belongings in the event of damage. For a few dollars a month, you can insure furniture, technology and other valuables.
Renters can also purchase a flood insurance policy to safeguard their finances after damage or loss from floodwaters.
Be sure to follow SouthState on Facebook for updates on inclement weather branch closings, updates on ATMs and more.
1. Cost of flooding calculator. FEMA. www.Floodsmart.gov
2. NFIP statistic. https://www.floodsmart.gov/why-buy-flood-insurance

In observance of Veterans Day, SouthState locations will be closed on Wednesday, November 11. SouthState Customer Care will be open 8 a.m. - 5 p.m. ET. Transactions initiated or scheduled on a holiday are processed the next business day.